


CDFA-Led Financial Modeling Before You Negotiate
Divorce in California often accelerates once financial disclosure begins. If your financial information is incomplete, inconsistent, or poorly organized, you lose leverage and increase the risk of costly outcomes.
My Divorce Solution (MDS) helps individuals in California build a verified Financial Portrait™ and model settlement scenarios before negotiations begin—so decisions are grounded in documentation, clarity, and economic reality.
Particularly in cases involving real estate portfolios, closely held businesses, executive compensation, stock options or RSUs, deferred bonuses, or variable income, financial modeling before negotiation can materially change long-term outcomes.
My Divorce Solution does not advocate for either side of a legal argument—we focus exclusively on building accurate, supportable financial analysis.
California Divorce Financial Factors That Influence Settlement Outcomes
In this section:
Community Property Framework and Classification Issues
California is a community property state. In general, assets and debts acquired during the marriage are presumed to be jointly owned and subject to equal division unless proven otherwise.
Why this matters financially:
Community property sounds simple, but classification disputes are often complex. Separate property claims, commingling of funds, business interests started before marriage but grown during marriage, stock grants issued over time, and inherited assets can all blur classification lines.
If documentation is incomplete or inconsistent, it becomes difficult to distinguish what is community versus separate property. This can materially affect asset division and settlement expectations.Note: In higher-asset cases, classification and valuation questions often involve partnership interests, restricted stock units (RSUs), stock options, deferred compensation plans, trust interests, inherited assets, or minority ownership stakes in private companies. These require careful documentation and clear modeling assumptions to avoid mischaracterization or unrealistic settlement expectations.

👉 Related resource: Dividing Divorce Assets with Family Law Attorney Joseph Willmore – A practical discussion on how California courts approach asset division, common classification challenges, and why documentation and valuation clarity significantly affect outcomes.
My Divorce Solution does not determine legal characterization, but we help organize documentation, model allocation scenarios, and quantify financial impact so discussions are grounded in numbers rather than assumptions.
New in 2026: Joint Petition (Joint Dissolution) and What It Changes Financially
Starting January 1, 2026, California allows spouses to file one joint petition together to begin a divorce or legal separation when they are aligned and intend to resolve everything by agreement.
Why this matters financially:
The benefit is not skipping the financial work—it’s doing it cleanly and early so the agreement is built on accurate inputs. If information is incomplete or unsupported, the process can stall or revert to a more traditional path.
Even in a cooperative setting, both parties must complete full financial disclosures and execute a comprehensive written agreement before anything becomes final. Clean documentation and well-modeled settlement terms reduce friction and prevent later disputes.👉 Related resource: California’s 2026 Joint Petition Explained: Amicable and Uncontested Divorce Options. Learn how California’s new joint filing option works, when it may reduce friction, and why complete financial disclosure and documentation are still required before an agreement becomes final.
My Divorce Solution helps clients prepare organized, verifiable financial exhibits and scenario comparisons so joint petitions are supported by accurate numbers from the start.
Equalization Payments and Buyout Structures
Even in a community property framework, division often requires one spouse to buy out the other’s interest in a home, business, or investment portfolio.
Why this matters financially:
The structure of a buyout matters as much as the headline number. A large equalization payment paid overtime without interest may significantly reduce real value. If funded by business distributions, stock liquidation, or real estate refinancing, liquidity timing and tax exposure can materially affect affordability.
If you are receiving payments, you must model cash flow gaps and risk. If you are paying, you must assess sustainability against real income volatility and long-term retirement goals.My Divorce Solution models cash flow impact, interest assumptions, tax consequences, and liquidity timing so proposed structures are evaluated before agreement.

Financial Disclosure Requirements in California
California requires formal financial disclosures, including preliminary and final declarations of disclosure, income and expense declarations, and detailed schedules of assets and debts.
Why this matters financially:
Disclosure documents form the foundation of settlement negotiations. Errors, omissions, or inconsistent valuation dates can undermine credibility and delay resolution. Income reporting must align with tax returns and pay documentation. Asset values must be supported by statements or appraisals.
Small inconsistencies compound quickly—especially when variable income, bonuses, or equity compensation are involved.My Divorce Solution helps clients organize disclosure-ready documentation and verify financial inputs before they are submitted, reducing downstream corrections and disputes.

Child Support Guideline Inputs in California
California uses a statutory formula that calculates child support based on income, custodial time percentages, tax filing status, and certain deductible expenses.
Why this matters financially:
The formula is mechanical, but the inputs drive the outcome. Misreporting income, misunderstanding overtime treatment, or inconsistently documenting childcare or health insurance costs can materially alter support calculations.
Variable income—such as commissions, bonuses, or self-employment earnings—requires careful documentation and averaging assumptions.My Divorce Solution helps clients prepare organized income documentation and scenario comparisons so proposed support numbers reflect economic reality.

Spousal Support Modeling Considerations
Spousal support in California involves both temporary and long-term considerations, often influenced by the length of marriage, earning capacity, and standard of living during the marriage.
Why this matters financially:
Support proposals may appear reasonable on paper but become unsustainable when modeled against post-divorce budgets, tax impacts, retirement timing, or fluctuating income streams.
Rejecting or accepting support terms without modeling affordability and long-term sustainability can create lasting financial instability.My Divorce Solution does not predict court outcomes or provide legal advice, but we model cash flow sustainability, retirement impact, and tax-adjusted outcomes so decisions are based on net numbers—not assumptions.

Housing Costs and Real Estate Tradeoffs in California
California real estate often represents the largest marital asset. Housing decisions require more than analyzing mortgage payments.
Why this matters financially:
Property taxes (especially under Proposition 13 rules), insurance, HOA fees, maintenance, refinancing costs, and potential capital gains exposure must all be considered.
A home that appears affordable at today’s mortgage rate may become unsustainable after refinancing or loss of certain tax protections. For clients holding multiple properties or investment real estate, modeling debt service, appreciation exposure, and liquidity timing can materially affect post-divorce stability.My Divorce Solution incorporates real-world cost drivers into “keep versus sell” and buyout modeling so decisions are based on sustainable numbers.

Property Tax Implications (Proposition 13 Considerations)
California’s Proposition 13 framework limits annual property tax increases for long-held properties. However, certain transfers or ownership changes may trigger reassessment depending on structure and exemptions.
Why this matters financially:
If you are keeping the home, you must understand whether your existing tax basis survives the transfer. If you are selling and purchasing another property, long-term tax exposure changes.
Overlooking reassessment risk can materially increase housing costs.My Divorce Solution does not advise on ownership structuring, but we flag these issues, model potential cost impacts, and help coordinate the right questions before finalizing real estate decisions.
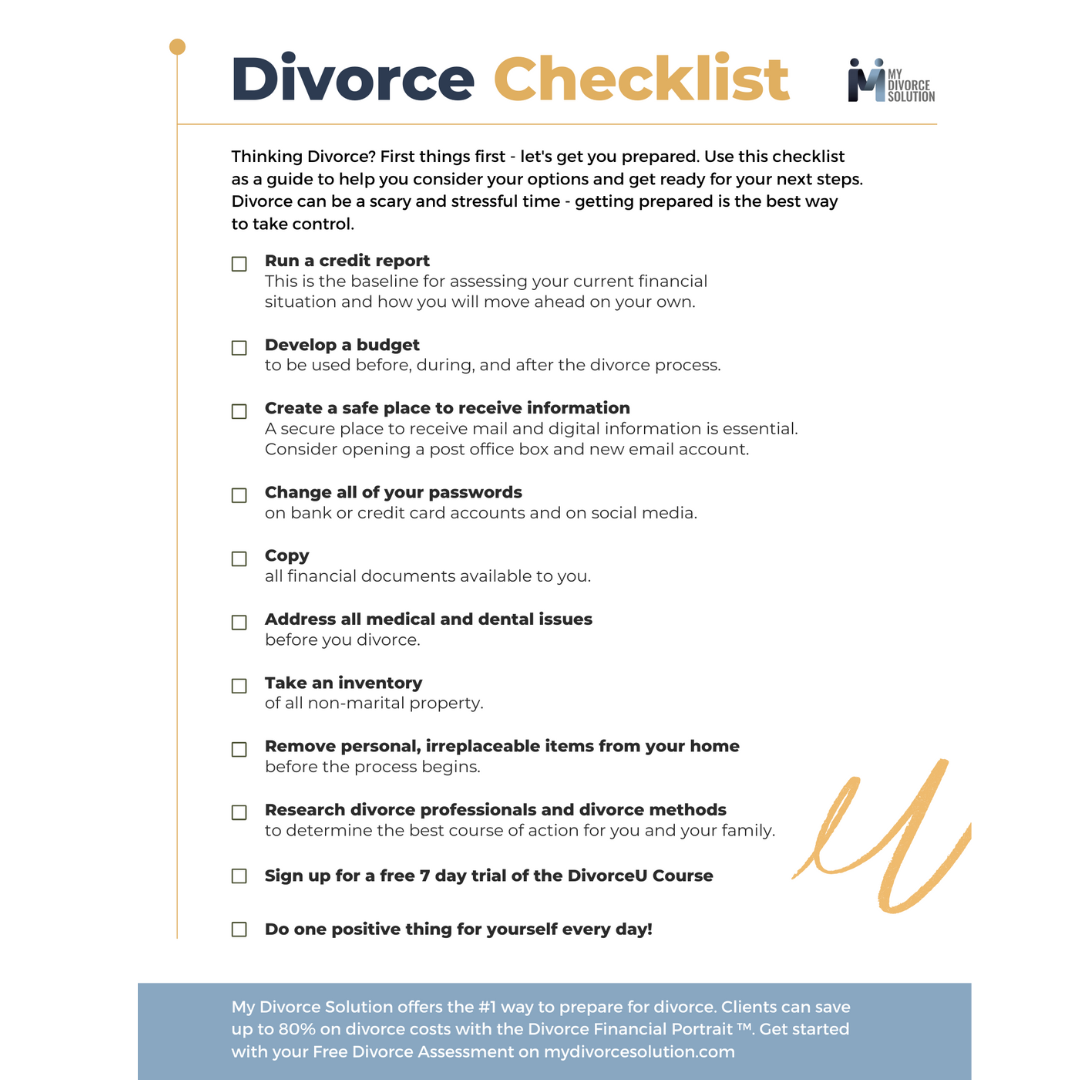
California Divorce Financial Document Checklist
This checklist reflects common financial documents used to build an accurate marital financial picture. It is not a list of court filing requirements.
Here’s what financial documents to prepare for a divorce in California:
- Recent paystubs, W-2s, 1099s
- Last 2–3 years of tax returns
- Bank, brokerage, and retirement account statements
- Mortgage and real estate records
- Insurance declarations and recurring housing costs
- Credit cards, loans, and lines of credit
- Business financial statements (if applicable)
In more complex cases, additional documentation may include business tax returns, partnership or operating agreements, equity award statements, deferred compensation summaries, trust documents, and multi-property operating statements. (My Divorce Solution)
California-Specific Document Checklist Add-Ons
In addition to standard financial documents, California divorces often require:
- Date of separation documentation – Emails, texts, lease agreements, or other evidence establishing when your marriage ended
- Prenuptial or postnuptial agreements – If applicable, with any amendments
- Stock option/RSU grant notices and vesting schedules – For any equity compensation received during the marriage
- Mortgage statements showing payment history – Relevant for Moore/Marsden calculations if one spouse made a separate property down payment
- Post-separation expense records – Receipts or statements showing who paid community debts after separation (for Epstein credit claims)
- Business formation documents and tax returns – If either spouse owns a business, including K-1s and operating agreements
- Deferred compensation or pension statements – PERS, CalSTRS, 401(k), or other retirement accounts subject to division
- Real property deeds and title documents – Especially if property was acquired before marriage or transmuted during
In more complex cases, additional documentation may include partnership or operating agreements, equity award statements, trust documents, and multi-property operating statements.

Working With Your Attorney or Mediator (Legal Liaison Support)
My Divorce Solution works alongside your attorney or mediator as a financial decision-support partner. We help translate financial data, assumptions, and modeled outcomes into clear, attorney-ready outputs.
Legal liaison support refers to financial coordination and clarification only. My Divorce Solution does not provide legal strategy, legal advice, or procedural guidance.
Common California Divorce Scenarios Worth Modeling
- Keep versus sell the marital home (including property taxes, insurance, and HOA costs)
- Retirement versus real-estate tradeoffs
- Support affordability with variable income (bonuses, commissions, self-employment, business owner)
- Date of separation timing and what it can change financially (income, earnings, savings, and planning assumptions going forward) (leginfo.legislature.ca.gov)
- Community versus separate interest in the home when one spouse owned it before marriage (Moore/Marsden)
- Post-separation mortgage, tax, and insurance payments and exclusive use of the home (Epstein credits and Watts charges)
- Hidden or disputed asset concerns

These issues can materially change the true buyout number or the realistic settlement range, so the best next step is to verify the underlying documents and model the financial impact, while your attorney advises on the legal position.
The MDS Financial Portrait™ for California Clients
Step 1: Organize and inventory assets, debts, income, and expenses
Step 2: Verify values and supporting documentation
Step 3: Model settlement and support scenarios to compare outcomes
Clients receive attorney-ready financial outputs designed to reduce back-and-forth, support efficient negotiations, and help avoid costly mistakes. This allows clients to enter mediation or settlement discussions with clarity, confidence, and defensible numbers.

Divorce Financial Freedom in California
Looking to turn financial knowledge into power during divorce?
When your assets are verified, your disclosures are organized, and your settlement scenarios are modeled before negotiation, decisions become clearer and less reactive.
Financial clarity doesn’t eliminate difficulty — but it changes the tone of every conversation that follows.